

CIS Abroad has joined forces with
CEA CAPA Education Abroad
As part of the CEA CAPA Education Abroad family, you'll find even more opportunities with our expanding global network.

Barcelona SAE has joined forces with
CEA CAPA Education Abroad
As part of the CEA CAPA Education Abroad family, you'll find even more opportunities with our expanding global network.
Financial Modelling and Derivatives- Period 4
Honors Program Program
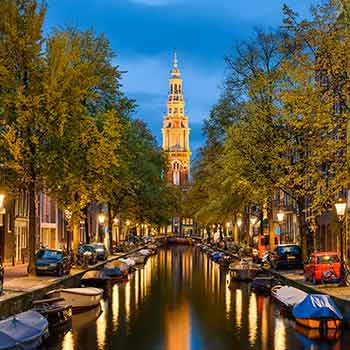
Amsterdam, Netherlands
Dates: 1/31/20 - 5/30/20
Financial Modelling and Derivatives- Period 4
OVERVIEW
CEA CAPA Partner Institution: Vrije Universiteit Amsterdam
Location: Amsterdam, Netherlands
Primary Subject Area: Finance
Instruction in: English
Course Code: E_IBK3_FMD
Transcript Source: Partner Institution
Course Details: Level 300
Recommended Semester Credits: 3
Contact Hours: 84
Prerequisites: Finance I and Quantitative Research Methods I and II.
DESCRIPTION
Central topics in financial modeling that will be discussed are:
- measures of risk in financial markets: variance and volatility of returns;
- trade-off between risk and return;
- estimation of average return and volatility;
- concepts of covariance and correlation; their estimation;
- risk and return of portfolios;
- diversification;
- universal risk measures: Value-at-Risk and Expected Shortfall;
- concept of efficient portfolio. Markowitz model;
- CAPM;
- risk premium and beta;
- multifactor models of risk.
Central topics in the part on derivatives that will be discussed are:
- types and characteristics of financial derivatives;
- use of derivatives in risk hedging;
- options: determining option price with the help of the binomial tree;
- sensitivities of options (Greeks);
- Black-Scholes model for option pricing and its assumptions;
- delta hedging of options;
- implied volatilities and volatility smiles;
Contact hours listed under a course description may vary due to the combination of lecture-based and independent work required for each course therefore, CEA's recommended credits are based on the ECTS credits assigned by VU Amsterdam. 1 ECTS equals 28 contact hours assigned by VU Amsterdam.
- measures of risk in financial markets: variance and volatility of returns;
- trade-off between risk and return;
- estimation of average return and volatility;
- concepts of covariance and correlation; their estimation;
- risk and return of portfolios;
- diversification;
- universal risk measures: Value-at-Risk and Expected Shortfall;
- concept of efficient portfolio. Markowitz model;
- CAPM;
- risk premium and beta;
- multifactor models of risk.
Central topics in the part on derivatives that will be discussed are:
- types and characteristics of financial derivatives;
- use of derivatives in risk hedging;
- options: determining option price with the help of the binomial tree;
- sensitivities of options (Greeks);
- Black-Scholes model for option pricing and its assumptions;
- delta hedging of options;
- implied volatilities and volatility smiles;
Contact hours listed under a course description may vary due to the combination of lecture-based and independent work required for each course therefore, CEA's recommended credits are based on the ECTS credits assigned by VU Amsterdam. 1 ECTS equals 28 contact hours assigned by VU Amsterdam.